Master of Tax
Course code: 742AB
March, June, July, August, December
AUD $49,984 (2026 indicative first year fee). Commonwealth Supported Places (CSPs) are not available
March, July
AUD $60,992 (2026 indicative first year fee)
IELTS 6.5: with no band less than 6.0
Course structure
Overview
Course structure
Students must complete 100 credit points in total. All international students are required to undertake Foundations of Tax Law. This subject provides a necessary grounding in Australian common law and statutory law of taxation, enabling a comparison with students’ home country tax systems. It provides the foundation for successful study in the other tax subjects studied in the course.
Students must complete at least 75 credit points from the prescribed lists and may select up to 25 credit points from the subjects offered in the Master of Commercial Law.
Subject timing and format
The Melbourne Law Masters program has been designed around the busy schedules of working professionals. Subjects are offered from February to December each year. Most subjects are taught intensively over five days, with some subjects taught for two hours each week during the semester.
Subjects delivered online will have a combination of pre-recorded lecture content, live sessions and discussion boards among other resources. On-campus subjects involve interactive, seminar-style classes in the Law Building in Melbourne.
Duration
Full-time students enrol in 50 credit points per semester (or half-year period) and have an expected course duration of one year. Part-time* students enrol in 25 credit points per semester (or half-year period) and have an expected course duration of two years. Semesters without enrolments require a student to apply for a leave of absence.
*Part-time enrolment is for domestic students only. Part-time students may reduce their study load to 12.5 credit points per half-year period and thus have a maximum course duration of four years.
Study Abroad at Oxford
Students enrolled in the Master of Tax also have the opportunity to study abroad at the University of Oxford.
Learn more
For detailed course and subject information, see the Handbook: Master of Tax.
Profile
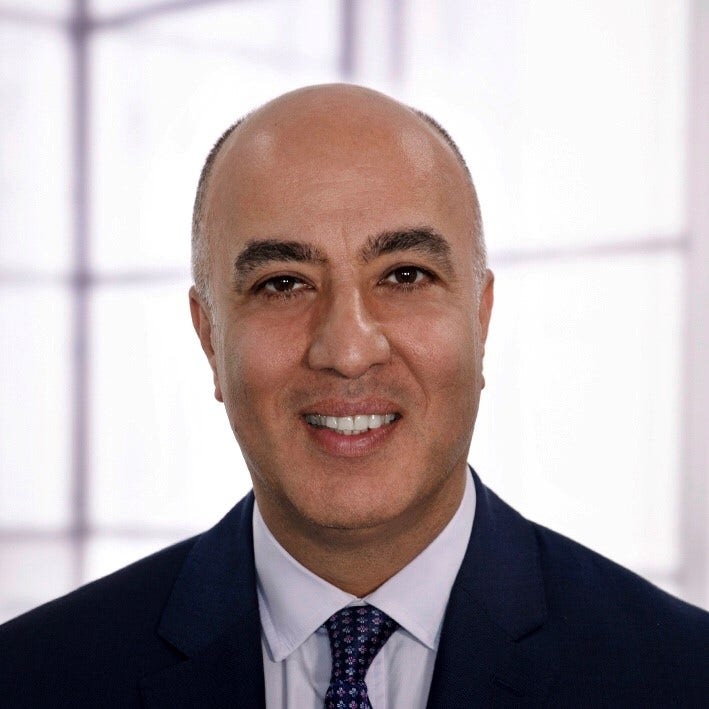
Professor Ali Noroozi
The wide-ranging and innovative tax specialisation at Melbourne Law School is the product of a creative partnership between the profession and the School.
— Professor Ali Noroozi
Explore this course
Explore the subjects you could choose as part of this degree.
Tax
Fundamental Tax subjects
| Accordion | |
|---|---|
| Capital Gains Tax: Problems in Practice · 12.5 pts |
This core tax subject examines the law, policy and structural features of capital gains tax (CGT) in Australia and considers and applies CGT rules in a number of different private and business contexts. The subject examines the operation of CGT in detail in the context of the treatment of information and goodwill, earn-outs, the application of CGT to non-residents, in relation to real estate transactions, litigation and the use of trusts and deceased estates. Indicative list of principal topics:
|
| Corporate Tax A · 12.5 pts |
This core tax subject examines the policies, detailed rules and current practical problems involved in the taxation of companies and shareholders in Australia, particularly at shareholder level. The lecturers are leading practitioners and they will consider the tax rules that apply to shares, corporate distributions, Australia‘s imputation system and the debt-equity integrity rules. This subject consists of a detailed examination of the tax rules applied to companies and shareholders in a domestic setting in Australia, with a focus on issues at the shareholder level. Indicative list of principal topics:
|
| Foundations of Tax Law · 12.5 pts |
This core tax subject examines the fundamentals of taxation, with a focus on Australia’s most important tax: the personal income tax. It engages with the tax law that is most relevant to legal and tax practice for individuals and businesses. This subject equips students to interpret statutory tax rules and apply judicial approaches, and to understand the policy and implications of tax reform in this fast-changing and challenging area of law. This subject is required for international tax students and is recommended for all masters students who have had little previous study or experience in tax law and wish to gain a solid grounding in the area. Indicative list of principal topics:
Important information about this SubjectAll international students are required to undertake Foundations of Tax Law. This subject provides a necessary grounding in Australian common law and statutory law of taxation, enabling a comparison with students’ home country tax systems. It provides the foundation for successful study in the other tax subjects studied in the course. This applies to students enrolled in the following courses:
More information on course planning in the Melbourne Law Masters. |
| Tax Administration · 12.5 pts |
Effective tax administration is at the heart of making tax policy work in practice. This subject takes you inside the workings of the Australian tax system — and beyond — to explore how laws are applied, enforced, and interpreted in the real world. We will examine the central role of the Federal Commissioner of Taxation and the Australian Taxation Office (ATO), uncovering how they exercise their powers, make decisions, and interact with taxpayers, tax professionals, and other government bodies at home and abroad. This subject offers a rare opportunity to view tax administration from multiple perspectives — as a taxpayer, a tax professional, a regulator, and a policy-maker — giving you a deeper understanding of how the system really works and how to navigate it successfully. Indicative list of principal topics:
This subject is taught by Professor Ali Noroozi who has more than 32 years of experience spanning government, private practice, and academia. He offers a unique insider’s perspective on tax administration. As Australia’s Inspector-General of Taxation from 2008 to 2018, he led an independent agency reviewing the actions of the ATO and the Tax Practitioners Board, driving reforms that shaped the modern tax landscape. His earlier career included senior roles in leading law and accounting firms in Australia and the UK. Students benefit not only from his deep technical expertise but also from the wealth of real-world insights and practical strategies he brings to the classroom. |
| Tax of Business and Investment Income · 12.5 pts |
This core tax subject is designed to explore in detail the fundamental principles of income tax, fringe benefits tax and capital gains tax in relation to business and investment. It will provide the requisite skills and knowledge to identify and better deal with income tax problems that arise in practice and in other tax subjects. The lecturers are leading practitioners or academics with extensive experience in the field. Indicative principal topics include:
|
Specialist Tax subjects
| Accordion | |
|---|---|
| Corporate Tax B · 12.5 pts |
This advanced corporate tax subject provides an in-depth analysis of the tax rules for Australia‘s largest public and private consolidated corporate groups, and the rules for use of losses by companies and corporate groups. It includes detailed discussion of the latest reforms in these highly technical areas of corporate tax practice, in light of tax policy applicable to companies and consolidated groups operating in Australia today. This subject is co-taught by experienced lecturers who combine academic and practitioner experience to deliver this advanced and commercially essential subject. Indicative list of principal topics:
|
| Goods and Services Tax · 12.5 pts |
This subject will examine Australia’s Goods and Services Tax (GST). The subject identifies the core legislative features in Australia’s GST contained in the A New Tax System (Goods and Services Tax) Act 1999. Indicative list of principal topics:
|
| Tax Avoidance and Planning · 12.5 pts |
This subject examines both general and specific anti-avoidance provisions in Australia and in comparable jurisdictions. The subject will examine in detail the provisions of Part IVA of the Income Tax Assessment Act 1936 (Cth), as well as its Goods and Services Tax (GST) equivalent, and consider the differences between permissible tax planning and impermissible tax avoidance. Indicative list of principal topics:
|
| Tax Litigation · 12.5 pts |
This specialist subject taught by leading members of the Victorian Bar specialising in tax, teaches all of the legal principles associated with tax litigation. It addresses the system of tax appeals, administrative and judicial review of decisions made by the Commissioner, evidence-gathering and the preparation of objections, tax appeal statements, affidavits, expert reports and legal submissions in a tax case. It explains how tax cases are tried and how they are dealt with at appellate level. It also covers the rulings system, the imposition and review of penalties and the Commissioner‘s rights of recovery. The focus of the subject is on the practical, and not theoretical, application of these principles. Indicative principal topics include:
|
| Tax of Employment and Personal Services · 12.5 pts |
This subject critically examines and provides students with a deep understanding of the legislative frameworks, judicial doctrines, and administrative practices that govern the taxation of employment income and personal services income in Australia. It also touches on broader employment and labour law concepts, in understanding more deeply the relevant taxation consequences relating to human capital and personal exertions, and from the perspective of all relevant parties. This subject has an Australian focus. Indicative list of principal topics:
|
| Tax Policy · 12.5 pts |
All governments need robust tax systems capable of funding them. Modern tax systems have also taken on other public policy roles, in income distribution and economic activity, and become integral to governments’ social and economic policies. Tax policy design thus entails a challenging mix of economic, social, legal, accounting and administrative policies - which has become more complex in a world of increasingly mobile capital and labour. This subject looks at Australia’s tax system and experience with reform over recent decades, comparing it with other countries. The subject will analyse the available tax bases, the interactions between the tax and transfer systems and issues of tax law design and administration. Indicative list of principal topics:
|
| Taxation of Superannuation · 12.5 pts |
Although relevant for all superannuation funds, this subject focuses heavily on self-managed superannuation funds (‘SMSFs’). This subject deals with the underlying policies, technical rules and current practical problems in relation to the taxation of SMSFs and their prudential management. In particular, it considers what investments and structures superannuation funds can use while still attracting concessional tax treatment along with how income is taxed, the treatment of contributions to those funds and the taxation of benefits paid. It also includes a detailed consideration of succession planning issues and how to apply those considerations in practice. Indicative list of principal topics:
|
| Taxation of Trusts · 12.5 pts |
This core tax subject will examine in depth the Australian income tax rules applicable to trusts, including significant new and ongoing reforms and policy developments. It will apply these rules to the range of applications of private trusts, such as unit trusts and family discretionary trusts. Indicative list of principal topics:
|
International and Comparative Tax subjects
| Accordion | |
|---|---|
| Comparative Corporate Tax · 12.5 pts |
Globalisation is driving corporate tax systems closer together and often into conflict. For many tax practitioners, it is now not enough to know their own corporate tax system—they must grapple with and question the operation of other corporate tax systems. This subject seeks to develop an ability to understand and analyse any corporate tax system and assess its impact on corporate decision-making. With a dedicated textbook (written by the presenter), this subject compares a number of influential and archetypal corporate tax systems (both common law and civil law) and assesses their behaviour in the context of practical problems. For tax professionals, this subject develops an ability to ask direct and informed questions about a foreign corporate tax system and discuss that system at a high level with foreign tax professionals. This subject will compare and analyse corporate income tax law in selected countries (Australia, China, Germany and the US, with some reference to the UK) and consider how these laws interface with corporate law. Participants will be encouraged to discuss other jurisdictions with which they are familiar and students are permitted to cover other countries in their research paper. The approaches adopted are analysed by reference to various policy options available. There is a particular focus on problems caused by the artificiality of corporations. Indicative list of principal topics:
|
| Comparative International Tax · 12.5 pts |
This subject will provide a detailed comparative analysis of the principal topics in international income taxation. Following an introduction to the foundations of international tax systems, the core principles of international income tax will be examined, with the different approaches taken by nations (developed, emerging, and developing countries) outlined and critiqued. This discussion will include the multilateralised bilateralism established by the tax treaty models of the OECD and UN, which form the basis for the more than 3.500 existing tax treaties. Based on a deeper understanding of those building blocks, the different perspectives of various nations with regard to the fair allocation of taxing rights, especially in the globalised and digitalised economy, will be explored. We will include a focus on the recent and ongoing (multilateral) attempts to stabilize the international tax system, such as the OECD Base Erosion and Profit Shifting (BEPS) project, the OECD Two Pillar Solution, ongoing transparency efforts, and work on the UN Framework Convention. It will also address the relationship between international trade and investment law and tax law, particularly amid rising trade tensions. Our subject equips students to analyse international tax issues using a comparative approach and to acquire a deep understanding of the underlying structural, institutional, and policy influences that have shaped and will shape international income tax systems. This knowledge is directly applicable to analysing international tax problems in any country. Indicative list of principal topics:
|
| International Tax: Advanced Topics · 12.5 pts |
This subject extends the study of international tax from fundamental principles to a range of advanced topics affecting inbound and outbound investment by companies, other entities, and individuals. The subject examines tax design and policy as well as the technical operation of Australian tax law. Recurrent themes include international tax avoidance, counter-measures developed through the OECD/G20 Base Erosion and Profit Shifting (BEPS) Project, Australia’s legislative and treaty responses to BEPS, and the counterpoint of avoiding or relieving international double taxation. The subject includes a critical examination of the policies underlying Australia’s rules and whether their technical implementation achieves their policy objectives. It also considers the ongoing reform of international tax rules, particularly through the BEPS Project. BEPS reforms are redefining the rules for countering international tax avoidance. This subject enables scholars and practitioners working in international tax to be aware of how international tax rules are being developed and reformed both globally and in Australia. Indicative list of principal topics:
|
| International Tax: Principles, Structure · 12.5 pts |
This core international tax subject is of central importance given Australia’s ever-growing role in the modern, global economy. and contemporary reforms intended to address the effects of digitisation and base erosion and profit sharing This subject covers the fundamental international income tax rules that apply where income or capital gains are derived in circumstances that have a connection with Australia. It considers Australia’s tax jurisdiction of residence and source, and relief from double taxation under domestic law. It also examines measures to prevent tax avoidance, such as controlled foreign company rules. This subject is designed to explore in detail the fundamental principles of Australia’s international taxation regime. The subject will examine both the issues of tax design and policy, and the relevant provisions in the legislation, cases and rulings. Indicative list of principal topics:
Note: Advanced treatment of tax treaties, controlled foreign corporations and trusts, thin capitalisation, transfer pricing, base erosion and profit shifting will be provided in the following suite of advanced and specialist international tax subjects.
|
| Tariffs and Taxes in China · 12.5 pts |
Chinese tariffs and tax law and policy play an important role in doing business with China. This subject offers a general introduction of the Chinese tariffs and tax regime, and also addresses the core elements of Chinese tariffs, value added tax, individual income tax, enterprise income tax, anti-tax avoidance measures and tax treaties which usually are the key factors influencing international trade and investment when involving China. Furthermore, the subject will bring you up to date through exploring the impact on China by the ongoing trade war and the international initiatives to tax digital economy, both of which are of high attention from business. Indicative list of principal topics:
|
| Tax Treaties · 12.5 pts |
Globally, countries have negotiated more than 3,000 bilateral tax treaties and the number of treaties continues to grow. Tax Treaties provides an in-depth examination of international tax treaties, regarding both inbound and outbound investment. This subject uses the Organisation for Economic Co-operation and Development (OECD) Model Treaty and Commentary and examines important tax treaties of Australia and its major trading partners. Professor Richard Vann has advised the OECD and country governments on these issues. This lively, engaging and relevant subject equips students to deal with the most topical and advanced issues of international tax in the application and interpretation of tax treaties, including the meaning of permanent establishment and taxation of business profits, residence and source, the treatment of investment income, exchange of information and avoidance of double taxation. Indicative list of principal topics:
|
| Transfer Pricing: Practice and Problems · 12.5 pts |
International transfer pricing is the price charged for the cross-border transfer of assets or services between associated enterprises in a multinational enterprise group. Transfer pricing is consistently identified in international surveys of multinational enterprises as the most important tax issue they face. Multinational enterprises have to deal with demands from the various jurisdictions in which they operate as national tax agencies implement measures to protect their revenue from cross-border trade between associated entities. This subject studies the Australian transfer pricing rules and their application. The Australian transfer pricing rules are based on the Organisation for Economic Co-operation and Development (OECD) Transfer Pricing Guidelines. This subject is designed for tax advisers, in-house tax managers and government officials, as well as those practising in transfer pricing. A background in transfer pricing is not required. Indicative list of principal topics:
|
Further subjects relevant to this course
| Accordion | |
|---|---|
| Cryptoassets in Global Context · 12.5 pts |
CSIRO’s Data61 digital research network describes blockchain technology as ‘a revolutionary new approach to database management’ that will prompt ‘significant changes in existing Australian industries’. Yet, despite significant investments of time and money by institutions around the world, we still lack robust proof of social or commercial benefit. Several years have passed since Bitcoin’s ‘Genesis Block’ was mined, but that foundational use case—digital cash without traditional intermediaries—has not challenged the legacy payments infrastructure. Where blockchain-based assets are used as monetary instruments rather than investments, those transactions are atypical in subject-matter and frequency. All of this begs the question: if the goal of blockchain technology is to eliminate ‘trusted third parties’, why is that something to aspire to? Is the answer to that question commercial or political? And, most importantly, is it correct? The aim of this subject is to answer these questions, and to do so by situating cryptoassets in their global context—as a matter of law, economics, politics and society. |
International students
All international students are required to undertake Foundations of Tax Law.
Compulsory subject
This subject provides a necessary grounding in Australian common law and statutory law of taxation, enabling a comparison with students’ home country tax systems. It provides the foundation for successful study in the other tax subjects studied in the course.
| Accordion | |
|---|---|
| Foundations of Tax Law · 12.5 pts |
This core tax subject examines the fundamentals of taxation, with a focus on Australia’s most important tax: the personal income tax. It engages with the tax law that is most relevant to legal and tax practice for individuals and businesses. This subject equips students to interpret statutory tax rules and apply judicial approaches, and to understand the policy and implications of tax reform in this fast-changing and challenging area of law. This subject is required for international tax students and is recommended for all masters students who have had little previous study or experience in tax law and wish to gain a solid grounding in the area. Indicative list of principal topics:
Important information about this SubjectAll international students are required to undertake Foundations of Tax Law. This subject provides a necessary grounding in Australian common law and statutory law of taxation, enabling a comparison with students’ home country tax systems. It provides the foundation for successful study in the other tax subjects studied in the course. This applies to students enrolled in the following courses:
More information on course planning in the Melbourne Law Masters. |